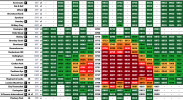
Precisely. XC, TPE and Avanti all have much depressed passenger figures (both absolute volumes and passenger-km) compared to other comparable operators. The common factor? Unreliability and severely reduced timetables. If it were an industry-wide phenomenon you'd also expect to see the likes of LNER, GWR, Northern etc. reporting comparable lower figures.
Unsurprisingly given that they are running between 60% and 65% of the services km that there were running pre Covid.
Whilst the likes of GWR are running 95% of services km.
There low rates of services by XC, TPE and Avanti (being longer distance TOC's) may mean that it's harder for other TOC's to get back to where they were because there's not the services to connect to.
Unfortunately it does appear that the biggest impact from those TOC's is likely to be felt in the North. Which makes a mockery of leveling up, when the government appear to be actively encouraging the strikes to continue by not going to the negotiating table.
Pre Covid £1bn of the £6bn in support for the railways was due to Network Rail debt, does National Highways (was Highways England) have the same requirement to cover their debt payments?
Those debts and other large NR costs mean that running every service which just about covers it's costs plus a bit is likely to result in less support from the government than if we tried cutting our way to a viable future. As unless we can cut NR costs (and running a few fewer trains isn't going to make much of a debt in that) the overall costs are likely to be broadly the same if not higher due to there just not being the passengers who are willing to use the railways due to poor reliability, poor frequency, etc.
Yes there maybe some places where cutting services would reduce TOC costs by more than the income. However there's currently likely to be a lot of services which could run and provide income to the government to cover a bit more off the NR costs. Do that enough and use and income may not be that far behind where they were.
Don't do that and the government will still be on the hook (even if every line closed in the UK) for £1bn of NR debt (and traffic congestion would be loads worse, so there'd have to be a significant spend on roads to cater for that - which would be impossible in London as we'd not have the land to provide the extra roads without impacting significantly on other properties).