• Our new ticketing site is now live! Using either this or the original site (both powered by TrainSplit) helps support the running of the forum with every ticket purchase! Find out more and ask any questions/give us feedback in this thread!

Nigel Farage and that bank account...

Status
Not open for further replies.

NeilCr

Member
Joined
26 Feb 2019
Messages
314
I don’t know much about Sam Fowles but came across this on a Twitter feed I follow (barrister)


It’s a long read and was written before the later events but it was the most in depth analysis I’ve come across. I read it at the time and then lost track of the story

Obviously it’s been attacked after the resignation and apology but it’s still worth a read if you have the time
 
Sponsor Post - registered members do not see these adverts; click here to register, or click here to log in
R

RailUK Forums

najaB

Veteran Member
Joined
28 Aug 2011
Messages
33,730
Location
Scotland
As has been said several times over the past few days, access to banking is an essential utility in todays increasingly cashless society, and people should have a legal right to at least a basic bank account, as is the case in countries such as France and Germany.
So then, it's a good thing that such a right exists in the UK.
 

MikeWM

Established Member
Joined
26 Mar 2010
Messages
4,962
Location
Ely
So then, it's a good thing that such a right exists in the UK.

But, as I've pointed out above and a number of times earlier in the thread, not for a business account, and he runs a perfectly legal and legitimate small business that requires banking facilities in order to operate. Is he supposed to just give up on that?
 

edwin_m

Veteran Member
Joined
21 Apr 2013
Messages
28,741
Location
Nottingham
Point taken, but not many people were aware of those articles from The Times, so there would be very little reputational risk to Coutts from keeping him as a customer.
Presumably anyone who'd had a cheque from him or seen his bank card would know who he banked with, and anyone he asked for a bank transfer could work it out from the sort code.
 

duncanp

Established Member
Joined
16 Aug 2012
Messages
4,856
So then, it's a good thing that such a right exists in the UK.

Such a right does not exist in the UK at the moment.

It used to before privatisation of the Post Office in 2013.
 

Busaholic

Veteran Member
Joined
7 Jun 2014
Messages
14,671
But, as I've pointed out above and a number of times earlier in the thread, not for a business account, and he runs a perfectly legal and legitimate small business that requires banking facilities in order to operate. Is he supposed to just give up on that?
Private banking describes itself as an elite service. In the case of Coutts it is at the heart of the same Establishment that Farage rails against for political purposes when it suits him. Now he cries ''foul'', but surely he should welcome Coutts's original action as evidence that he was right in the first place, though I doubt even he believes that! If a private bank decides for whatever reason it wants nothing more to do with a customer then. so long as it returns any money held and it's not being done for reasons of race or gender, it should remain a private matter between the two. rather than be exploited for spurious political reasons.

== Doublepost prevention - post automatically merged: ==

Such a right does not exist in the UK at the moment.

It used to before privatisation of the Post Office in 2013.
Yes. I believe you're probably right there.
 

najaB

Veteran Member
Joined
28 Aug 2011
Messages
33,730
Location
Scotland
Such a right does not exist in the UK at the moment.

It used to before privatisation of the Post Office in 2013.
I'm not sure that is correct. The Payment Account Regulations (2015) appear to place a legal obligation on the largest banks to provide basic accounts to everyone. Specifically:

Non-discrimination in the provision of payment accounts
18.—(1) A credit institution must not discriminate against consumers legally resident in the European Union by reason of their nationality or place of residence or by reason of any other ground referred to in Article 21 of the Charter of Fundamental Rights of the European Union when those consumers apply for or access a payment account.

(2) The conditions applicable to holding a payment account with basic features must not be discriminatory.
and
Duty to offer a payment account with basic features
22.—(1) A designated credit institution must offer a payment account with basic features to any consumer who—

(a)applies for a payment account with basic features on or after 18th September 2016; and
(b)meets the eligibility criteria set out in regulation 23.
(2) Where a designated credit institution does not offer a service referred to in regulation 19(1) to consumers holding payment accounts with it which are not payment accounts with basic features, it is not required to offer that service as part of a payment account with basic features.

Eligibility criteria
23.—(1) In order to be eligible for a payment account with basic features offered by a designated credit institution (“B”), a consumer must be legally resident in the European Union, and must either—

(a)not hold a payment account with any United Kingdom credit institution that has at least the features set out in regulation 19(1); or
(b)be ineligible for all payment accounts offered by B that are not payment accounts with basic features.
(2) For the purposes of paragraph (1)—

(a)consumers legally resident within the European Union include—
(i)consumers with no fixed address;
(ii)asylum seekers within the meaning of section 94 of the Immigration and Asylum Act 1999(1) (interpretation); and
(iii)consumers who have not been granted a residence permit but whose expulsion is impossible for legal or practical reasons;
(b)a consumer is not to be considered to hold a payment account where the consumer makes a declaration that the credit institution with which the payment account is held has given notice that the payment account is to be closed.
(3) A designated credit institution must verify whether a consumer falls within paragraph (1)(a), unless it chooses to rely on a declaration made by the consumer to that effect.
 

fgwrich

Established Member
Joined
15 Apr 2009
Messages
10,651
Location
Hampshire
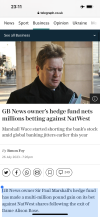
Well, this has taken an interesting little turn this evening. Farage is of course an employee of GB News, alongside certain high profile MPs in the form of 30p Lee Anderson and Rees Mogg aka the Haunted Pencil.

I’ll quote the article as it’s behind the Telegraph’s paywall:
“GB News owner Sir Paul Marshall’s hedge fund has made a multi-million pound gain on its bet against NatWest shares following the exit of Dame Alison Rose.

Regulatory filings show that Marshall Wace has the biggest short position in the lender’s shares meaning it stands to gain from falls in the bank’s market price.

The fund netted paper gains of around £5m on Wednesday after NatWest’s share price slumped more than 3.7pc after the departure of its chief executive Dame Alison Rose, which wiped more than £850m off the value of the lender.

While the gain represents a tiny sum relative to Marshall Wace’s more than $60bn in assets under management, it may give Sir Paul extra satisfaction given his stance against “woke” business culture.

GB News also employs Nigel Farage as a host and he has used his show as a platform to attack NatWest for “debanking” him.

However, it is understood Marshall Wace’s bet against NatWest is mostly computer-driven.

The hedge fund has software it calls TOPS (Trade Optimised Portfolio System), which analyses the views of analysts and economists and gives indications where to invest.

Marshall Wace first disclosed that it was building a short position against NatWest in March, when fears were growing over the health of the global financial system following the collapses of Silicon Valley Bank and Credit Suisse.

At the start of last month it had borrowed 0.8pc of the shares to profit from price falls, but has since trimmed the bet to 0.59pc, according to data from the Financial Conduct Authority.

Sir Paul, whose son Winston was a member of the band Mumford and Sons, has been a prominent backer of Brexit, calling it “a huge opportunity for the UK”.

Last year, alongside Legatum, a Dubai-based group founded by the billionaire Christopher Chandler, he bought out the US entertainment giant Warner Bros. Discovery and GB News co-founders Andrew Cole and Mark Schneider of their stake in the news network.

Last year, Sir Paul shared a pot of more than £720m with a group of 23 partners after his London-based hedge fund posted a surge in profits.

Marshall Wace declined to comment.”

 

Attachments

  • IMG_5135.png
    IMG_5135.png
    3.3 MB · Views: 8

Parjon

Member
Joined
27 Oct 2022
Messages
518
Location
St Helens
so long as it returns any money held and it's not being done for reasons of race or gender
Why only race or gender, and not any of the other legally protected characteristics?

Noting that religion and philosophical beliefs are included in those.

Regardless, what I feel sure of is that accessing and distributing private information about someone in breach of their data protection rights is a criminal offence. A bank employee passing information about a customer to external parties not entitled to receive that information is about as serious as it gets, for obvious reasons.

Why do rich people get to pass that off as "an error of judgement"? If it was an employee in the call centre the police would have been called.
 

takno

Verified Rep - Traksy
Joined
9 Jul 2016
Messages
6,601
Regardless, what I feel sure of is that accessing and distributing private information about someone in breach of their data protection rights is a criminal offence. A bank employee passing information about a customer to external parties not entitled to receive that information is about as serious as it gets, for obvious reasons.

Why do rich people get to pass that off as "an error of judgement"? If it was an employee in the call centre the police would have been called.
It isn't to the best of my knowledge a criminal matter, and I have never once heard of the police being called, and very much doubt they would respond even if somebody did call them.

== Doublepost prevention - post automatically merged: ==

Well, this has taken an interesting little turn this evening. Farage is of course an employee of GB News, alongside certain high profile MPs in the form of 30p Lee Anderson and Rees Mogg aka the Haunted Pencil.

I’ll quote the article as it’s behind the Telegraph’s paywall: ...Sir Paul, whose son Winston was a member of the band Mumford and Sons, has been a prominent backer of Brexit, calling it “a huge opportunity for the UK”....
Well I never. As if there wasn't an already almost inexhaustible supply of reasons to dislike Mumford and Sons
 

najaB

Veteran Member
Joined
28 Aug 2011
Messages
33,730
Location
Scotland
Regardless, what I feel sure of is that accessing and distributing private information about someone in breach of their data protection rights is a criminal offence. A bank employee passing information about a customer to external parties not entitled to receive that information is about as serious as it gets, for obvious reasons.
Yes. This is a breach of data protection laws.
 

brad465

Veteran Member
Joined
11 Aug 2010
Messages
11,544
Location
Taunton or Kent
Well, this has taken an interesting little turn this evening. Farage is of course an employee of GB News, alongside certain high profile MPs in the form of 30p Lee Anderson and Rees Mogg aka the Haunted Pencil.

I’ll quote the article as it’s behind the Telegraph’s paywall:
Interesting that The Telegraph are reporting this, a paper that agrees with a lot of what Farage proclaims.
 

najaB

Veteran Member
Joined
28 Aug 2011
Messages
33,730
Location
Scotland
It isn't to the best of my knowledge a criminal matter...
I need to double-check, but my 1am brain is telling me that you can be criminally prosecuted for gross breaches of the Data Protection Act.
 

takno

Verified Rep - Traksy
Joined
9 Jul 2016
Messages
6,601
I need to double-check, but my 1am brain is telling me that you can be criminally prosecuted for gross breaches of the Data Protection Act.
The stretch here is imagining that it's a gross breach, or that anybody in a more junior role would ever end up being prosecuted. Privacy at banks is more important than at other places, but revealing that somebody hasn't got a three million quid in your bank after they themselves revealed a lot of information isn't in the same league as revealing health or legal secrets.

If prosecution were likely or common then our data protection videos would be threatening that rather than slightly toothlessly saying you might be fired.
 

duncanp

Established Member
Joined
16 Aug 2012
Messages
4,856
I'm not sure that is correct. The Payment Account Regulations (2015) appear to place a legal obligation on the largest banks to provide basic accounts to everyone. Specifically:

I wasn't aware of those regulations.

I think a lawyer needs to look at these regulations and give an opinion as to whether they confer a legal right to at least a basic banking account to anyone who is legally resident in the UK.

If the regulations do confer such a right, the government needs to spell this out to the banks, and reiterate that they must not close a customer's account if such a closure would lead to the customer being unable to access basic banking services.

If you read the stories that have been in the news media over the past few days, there are definitely cases of people who have had accounts closed with no alternative account in place.

If the regulations do not confer such a right, then the law needs to be changed so that everyone legally resident in the UK has the right to a basic bank account.

The government also needs to look at the money laundering regulations and politically exposed person regulations to make sure that they are fit for purpose.

Part of the problem I think is that the banks have been over zealous in applying these regulations as well as acting as judge, jury and executioner. (ie. some anonymous person at the bank says you are guilty, or even just suspected, of money laundering and closes your account as a consequence, with no come back or right of appeal)
 

yorksrob

Veteran Member
Joined
6 Aug 2009
Messages
44,414
Location
Yorks
Well, this has taken an interesting little turn this evening. Farage is of course an employee of GB News, alongside certain high profile MPs in the form of 30p Lee Anderson and Rees Mogg aka the Haunted Pencil.

I’ll quote the article as it’s behind the Telegraph’s paywall:

If only we had a sovereign wealth fund with such software.

Perhaps we should skim a couple of percent off of all these private funds to start one.
 

Falcon1200

Established Member
Joined
14 Jun 2021
Messages
6,598
Location
Neilston, East Renfrewshire
The banks who declined to provide full current accounts were well within their rights to refuse his custom for whatever reason they wanted.

And on that we will have to agree to disagree; Banks are there to provide banking services, not decide who in their opinion is nice and who is not.

And Farage was offered a NatWest account to replace his Coutts one.

In which case, one would have to ask; Given that Coutts and NatWest are part of the same group, what on earth was the point of closing his Coutts account in the first place?
 

ainsworth74

Forum Staff
Staff Member
Global Moderator
Joined
16 Nov 2009
Messages
31,126
Location
Redcar
Banks are there to provide banking services, not decide who in their opinion is nice and who is not.
Is the same true of all private businesses?


In which case, one would have to ask; Given that Coutts and NatWest are part of the same group, what on earth was the point of closing his Coutts account in the first place?

Presumably becuase he no longer met the criteria for a Coutts account. His political views clearly paid a role (Coutts admit as much) but does anyone really think that if he had say £5m being handled by them they would have closed the account? No, they'd have held their noses and carried on doing business with him.
 

Falcon1200

Established Member
Joined
14 Jun 2021
Messages
6,598
Location
Neilston, East Renfrewshire
Is the same true of all private businesses?

Why should it not be, as long as no illegality is involved?

Presumably becuase he no longer met the criteria for a Coutts account. His political views clearly paid a role (Coutts admit as much) but does anyone really think that if he had say £5m being handled by them they would have closed the account?

I'm sure I have seen it stated that others have fallen below Coutt's wealth criteria but did not have their accounts closed as a result. But if that criteria was indeed the reason, why even bother with the other stuff about his political views, it was completely unnecessary?
 

Parjon

Member
Joined
27 Oct 2022
Messages
518
Location
St Helens
prosecution were likely or common then our data protection videos would be threatening that rather than slightly toothlessly saying you might be fired.
Don't know what data protection videos you watch. Our annual online training module sets out the maximum sentence.

Making staff aware of the consequences, and other corruption protection measures, are why prosecution isn't common. However it has occurred and not just at banks.

While one might argue that any breach in question may be "less serious", in fact I feel it would be more so because she is a senior leader. I don't see why it doesn't merit criminal investigation to establish the facts.
 

ainsworth74

Forum Staff
Staff Member
Global Moderator
Joined
16 Nov 2009
Messages
31,126
Location
Redcar
Why should it not be, as long as no illegality is involved?
Excellent I'm glad we agree, I just hope that we will see a similar furore in the media the next time a private business is caught out discriminating against someone and refusing service as a result. Of course in this case the issue wasn't just they didn't like him it was that he cost them money.
I'm sure I have seen it stated that others have fallen below Coutt's wealth criteria but did not have their accounts closed as a result.
But who were they? Nigel Farage was a figure in the public eye who had further disclosed his relationship with Coutts meaning that he was quite an expensive client for them to maintain. If there are similar figures who have made it publicly known that they bank with Coutts who are also in the media eye and political exposed and therefore come with extra costs to the point that Coutts is probably losing money on them then it would be interesting to know why those account haven't also been closed. But I suspect that those individuals, should they exist, don't come with as many costs as Farage did.
But if that criteria was indeed the reason, why even bother with the other stuff about his political views, it was completely unnecessary?
Because his relationship with Coutts was known (not well know, but known) his political views were therefore seen as a reputational risk. Considering the extra costs of providing him with banking services and the fact that they were no longer making money as a result of that it doesn't seem crackers that they would go on to close his account.

The bigger issue, for me, that is getting lost in the fud of "WOKE BANKING TAKES OVER BRITAIN" is how we've got to the point that politicians of any stripe seem to find it hard to open and maintain bank accounts because of all the extra anti-money laundering and bribery protections that apply to the accounts of such individuals. That doesn't seem ideal for anyone. Equally I do actually think there's a good point about the way banks can close (or freeze) accounts with no information as to the reasons. You don't have to go to far to find people asking for advice about a frozen bank account who can get absolutely no explanation out of the bank as to why their account is frozen being told that it's probably because of anti-money laundering or other fraud concerns.

Rather than worrying about famed man of the people Nigel Farage (who had an account closed with the same bank that the Royal Family use, not exactly you common high street bank) and the "WOKE BANKING LOBBY", I'd be rather more worried about the issues facing politicians of all stripes and ordinary people who get caught up in byzantine arrangements of anti-fraud and money laundering provisions.

But yes, lets all go on and on about poor Mr Farage instead...
 

simonw

Established Member
Joined
7 Dec 2009
Messages
1,410
Such a right does not exist in the UK at the moment.

It used to before privatisation of the Post Office in 2013.
I don't understand your last sentence, the Post Office is state owned.
 

Howardh

Established Member
Joined
17 May 2011
Messages
9,797
If I can take Farage out of the topic, I worry about "debanking" myself.

What exactly happens to your money if a bank decided to "debank" you out of nowhere for no good reason? You are supposed to be informed (what if you miss that information), do they send you a cheque with your balance, or do they just hold the money as long as they like (and pocket the interest)?

Worried so much that I might go to one of my building societies and ask for a current account, debit and credit card as back-up. At least if bank "A" closes, I can fall back on bank "B" as long as all accounts aren't closed in common.

Also, I'd be getting my solicitor to write to them asking for more information and a meeting with an executive, although I doubt they would be so accommodating.

So back to the Person In Question, for once he might have done us all a favour.
 

nw1

Established Member
Joined
9 Aug 2013
Messages
9,430
Rather than worrying about famed man of the people Nigel Farage (who had an account closed with the same bank that the Royal Family use, not exactly you common high street bank) and the "WOKE BANKING LOBBY", I'd be rather more worried about the issues facing politicians of all stripes and ordinary people who get caught up in byzantine arrangements of anti-fraud and money laundering provisions.

But yes, lets all go on and on about poor Mr Farage instead...
All I can say is, if the press spent as much effort in fighting the real problems of the contemporary UK, such as the state of the NHS, the cost of living, the state of public services in general, and potential threats to job security from automation and recent developments in AI, as they did feeling sorry for poor oppressed Nigel Farage, the country would be a much better place.

Farage is no hero, he is a hardline right-winger who has directly caused great damage to the country. A faux "man of the people" who lives an exceptionally privileged life. Regardless of the rights and wrongs of this bank account case, he is not someone who needs a lot of sympathy, nor a lot of energy devoted to him. He can always take his bank account elsewhere.

A post above raised concerns about some Muslims being denied basic banking services. That is a far greater concern than access to an elite bank account by some privileged politician and media "star" who possibly no longer meets the criteria for such an elite account.

I haven't seen any headlines recently (as I am out of the country) but if they are really going on about the "WOKE BANKING LOBBY" it just sums up what a sorry state the country is in. Who gives a damn about Nigel Farage, really? There are more important things going on which are far more worthy of energy being devoted to them.

It's funny that a lot of the populist right will say precisely what I'm saying about Farage, about their own personal hate figures from the liberal wealthy, such as Gary Lineker. Yet when their hero Farage is "mistreated", they're up in arms...
 
Last edited:

jon0844

Veteran Member
Joined
1 Feb 2009
Messages
30,943
Location
UK
What exactly happens to your money if a bank decided to "debank" you out of nowhere for no good reason? You are supposed to be informed (what if you miss that information), do they send you a cheque with your balance, or do they just hold the money as long as they like (and pocket the interest)?

They will either give you your money back (which I'm sure you could withdraw as cash if you didn't have another account) or call in your loans/mortgages with maybe 30 days notice or whatever is in the T&Cs.

If the account was frozen, I'd expect that to be due to some sort of criminal investigation in which case you'd be getting advice from a lawyer.
 

Howardh

Established Member
Joined
17 May 2011
Messages
9,797
They will either give you your money back (which I'm sure you could withdraw as cash if you didn't have another account) or call in your loans/mortgages with maybe 30 days notice or whatever is in the T&Cs.

If the account was frozen, I'd expect that to be due to some sort of criminal investigation in which case you'd be getting advice from a lawyer.
Of course they "freeze" an account on death, however money (ie. interest, outstanding pensions) still gets paid in, in my experience nothing went out (outstanding payments) until probate when the money is then released to the executioner.
 

jon0844

Veteran Member
Joined
1 Feb 2009
Messages
30,943
Location
UK
Of course they "freeze" an account on death, however money (ie. interest, outstanding pensions) still gets paid in, in my experience nothing went out (outstanding payments) until probate when the money is then released to the executioner.

But you said 'What exactly happens to your money if a bank decided to "debank" you out of nowhere for no good reason?' which is a bit different to, erm, dying.
 

Howardh

Established Member
Joined
17 May 2011
Messages
9,797
But you said 'What exactly happens to your money if a bank decided to "debank" you out of nowhere for no good reason?' which is a bit different to, erm, dying.
Sorry, just trying to make the point that money can still go into a "frozen" account and used that as an example. However, it's easy to unlock a frozen account on death with probate, however not so easy if it's frozen as part of an investigation, and I'm unaware of any rules r/e that, example, how long the bank can do that (limitless?) and what the client can do about it to get it unfrozen.
 

jon0844

Veteran Member
Joined
1 Feb 2009
Messages
30,943
Location
UK
If you were in such a situation where your account was frozen not by the bank but as a request by the police or whatever agency, you'd be dealing with everything via your legal team.

At some point they'd have to charge you with a crime or drop everything and the account would be unfrozen, surely?
 

ainsworth74

Forum Staff
Staff Member
Global Moderator
Joined
16 Nov 2009
Messages
31,126
Location
Redcar
At some point they'd have to charge you with a crime or drop everything and the account would be unfrozen, surely?
From what I've seen of people asking for advice online when their accounts are randomly frozen the usual problem is the complete lack of any information about what's going on and how long it might take for things to get unfrozen. If you ring the bank they'll just remain tight lipped. If you've only got the one bank account this can rapidly cause serious issues.

Here's someone who was frozen out for three months:

Hi guys - am a UK (England) resident with a bank account in a popular bank (think Barclays, HSBC, Santander etc - don't want to post the name incase it compromises my identity).

Three months ago I suddenly could no longer use my bank cards. When I went to the bank, turned out my assets have all been frozen - my current account and my savings account (which contained around 50k in savings that I've been saving for upwards of 10 years). After some back and forth, the bank informed me they legally did not have to tell my why the froze my account nor did they have to give me any updates, and I would have to wait for them to "complete their investigation" before I regained any access to my bank account. I tried to fight them on this for a couple of weeks, but due to a) not having any money from being frozen out of my bank account and b) a lot of resistance from them and refusal to cooperate, I eventually accepted it and waited for them to finish their investigation.

I have never done anything illegal, all this money I have saved from my job for the last 10 years, so I have no idea why my bank account was frozen. Only reason I can think is I was born abroad - but surely they wouldn't close it because of that?

It has now been 3 months and I've not heard a peep from them, and have not regained access to my bank account. I desperately need the money for mortgage payments and to pay for school for children. The bank still insist there's "nothing they can do" but its been 3 months, I'm getting desperate. I've been having to rely on family for money, which I cannot keep doing.

I don't have money for lawyers (since they froze my accounts) and am at my wits end. Could someone please give some advice - either how much longer am I expected to wait, or is there anything I can do? Thank you in advance

Googling around shows various tales of woe with banks freezing customer accounts with no warning, limited/no explanation and no estimate on when the account will be unfrozen. It would be much more helpful if Farage and the friendly right wing media directed their attention at this sort of issue rather than going straight into the culture war "BANKS GONE WOKE! CAN'T EVEN HAVE A SINGLE OPINION ANYMORE!" angle.
 
Status
Not open for further replies.

Top