• Our new ticketing site is now live! Using either this or the original site (both powered by TrainSplit) helps support the running of the forum with every ticket purchase! Find out more and ask any questions/give us feedback in this thread!

Interest Rate Rise - a good idea ?

Status
Not open for further replies.

Nicholas Lewis

Established Member
Joined
9 Aug 2019
Messages
8,005
Location
Surrey
Response from Treasury and Bank of England "too little, too late" according to some.
We'll probably see tomorrow whether or not the pound continues to "fall" according to their predictions or whether things stabilise overnight, although markets remain open around the world of course.
Rishi Sunak is probably working up a good line in "I told you so" speeches, probably not for tomorrow of course.
Shorters smell blood and won't be moved by hollow statements but I suspect we won't see much more significant downward shifts as the likes of Odey will lock in the 100's of millions hes made and then regroup. The other thing that's helping here is a heavy run back in the price of oil and even gas has dropped back to just high now rather than stupidly high is giving the bank some breathing space.
 
Sponsor Post - registered members do not see these adverts; click here to register, or click here to log in
R

RailUK Forums

Dai Corner

Established Member
Joined
20 Jul 2015
Messages
6,990
Response from Treasury and Bank of England "too little, too late" according to some.
We'll probably see tomorrow whether or not the pound continues to "fall" according to their predictions or whether things stabilise overnight, although markets remain open around the world of course.
Rishi Sunak is probably working up a good line in "I told you so" speeches, probably not for tomorrow of course.
Boris said 'I'll be back' in his final speech as PM.

If it doesn't turn out well for the Truss Government I could see him and Rishi fighting the next election as leader and chancellor-designate
 

david1212

Established Member
Joined
9 Apr 2020
Messages
1,754
Location
Midlands
The RPI is currently ~12% and CPI ~10%. Once winter energy use kicks in even with the domestic and business capping these will go up.

Right now against the lower CPI anything less than 10% is a real loss e.g. 2% interest is an 8% loss before considering tax deductions outside of an ISA and the £1000 allowance.

Stocks and shares are even worse as many funds have dropped rather than grown over the last 12 months. A drop of 5% is a real loss of 15% against the CPI.

The railway unions are currently concentrating on salary plus terms and conditions. How long before a real drop in pension funds values becomes a headline issue?
 

66701GBRF

Member
Joined
3 Jun 2017
Messages
913
Virgin Money and Halifax have temporarily wirhdrawn some of their mortgage products.

While I missed the boat the last couple of weeks having been away, I'm glad I was able to fix my mortgage this morning...although obviously at a higher rate than I was paying.
 

najaB

Veteran Member
Joined
28 Aug 2011
Messages
33,627
Location
Scotland
The railway unions are currently concentrating on salary plus terms and conditions. How long before a real drop in pension funds values becomes a headline issue?
It's already an issue for me - my pensions are down around 13% so far this year (and that's just valuation, not taking inflation into account). Fortunately I've got 20 years to go before retirement so it's not an immediate concern, but it must be very concerning to anyone who's just a few years away.
 

DelayRepay

Established Member
Joined
21 May 2011
Messages
2,929
It's already an issue for me - my pensions are down around 13% so far this year (and that's just valuation, not taking inflation into account). Fortunately I've got 20 years to go before retirement so it's not an immediate concern, but it must be very concerning to anyone who's just a few years away.

My SIPP is in a similar position. On the bright side it means that my monthly contributions buy more units, so when things pick up (as they always do) I'll be better off.
 

Wynd

Member
Joined
20 Oct 2020
Messages
741
Location
Aberdeenshire
The RPI is currently ~12% and CPI ~10%. Once winter energy use kicks in even with the domestic and business capping these will go up.

Right now against the lower CPI anything less than 10% is a real loss e.g. 2% interest is an 8% loss before considering tax deductions outside of an ISA and the £1000 allowance.

Stocks and shares are even worse as many funds have dropped rather than grown over the last 12 months. A drop of 5% is a real loss of 15% against the CPI.

The railway unions are currently concentrating on salary plus terms and conditions. How long before a real drop in pension funds values becomes a headline issue?

Including commodity price inflation, the depreciation in the currency, and the fact that the government measures of RPI/CPI are inapplicable to many who don't buy "small caged mammals" on a monthly basis, (yes, that is in fact one of the inflation items). True inflation is well north of 20%.

For those of us who watch the grocery bill closely, 9% inflation is a bad joke. 9% a quarter maybe. And if its not prices rising, its the size of the portions that are getting drastically smaller.

Rising mortgage rates will feed inflation, as will rising real oil prices, given Sterling now buys you 20% fewer dollars than 6 months ago.

As for pensions, some are fortunate enough to have the option of investing their pension in market funds with little to no exposure to UK equities which are now some of the most depressed on a valuations basis, in the developed world.

The Bank of England is now forced to act. Implied rates are over 4.5%. The base rate is 2.25%. We won't see 15% base rates IMHO, because that would render millions of people homeless. Personal indebtedness is now far higher than in the 70's, a lot else has changed in half a century.

4% base rate by Christmas seems plausible. That would translate to 6% mortgages, which is really going to hurt if all you've ever known are 1-3% mortgages.

 

david1212

Established Member
Joined
9 Apr 2020
Messages
1,754
Location
Midlands
It's already an issue for me - my pensions are down around 13% so far this year (and that's just valuation, not taking inflation into account). Fortunately I've got 20 years to go before retirement so it's not an immediate concern, but it must be very concerning to anyone who's just a few years away.

Just a year ago after review my combined funding pot ( personal pension ( I have never had a workplace pension / employer contributions other than those to the second state pension ), cash ISA, stocks and shares ISA, inherited saving certificates ) was on track to my retirement plans. These plans are now out of the window.
I doubt that compared to April 2022 by April 2024 the increase in the CPI will be much less than 25%. Further if there was an index of energy, food, council tax, water and other essentials I suspect that would be higher than 25%.
If my pot increased by 10%, which right now is very optimistic, the shortfall is 15%. To recover that I will have to work two years.
The state pension increases will have to match the CPI so £9500 would become ~£12000. If the tax threshold stays at £12570 instead of being able to add £3000 pa tax free that would be taxed so £2400 net. It would be leisure that looses out e.g. national & heritage railways.

At least I am still working and, subject to neither individual redundancy or the company closing, I can carry on working. Had all this happened after I had retired a very different situation.
 

najaB

Veteran Member
Joined
28 Aug 2011
Messages
33,627
Location
Scotland
4% base rate by Christmas seems plausible. That would translate to 6% mortgages, which is really going to hurt if all you've ever known are 1-3% mortgages.
I would be very pleasantly surprised if the base rate is only at 4%. 5 or even 6% doesn't seem to be too wild an idea.
 

johncrossley

Established Member
Joined
30 Mar 2021
Messages
4,404
Location
London
I have a fair bit in savings and one set of shares. The key is banks are easy to deal with, follow the rates and move as and when. The phrase "minimal risk" is not "no risk"! At least with a bank or building society there is an £85k guarantee.

Why are you so concerned about the £85K guarantee? It is meaningless in the context of investing. If you have the most vanilla investment in the world (a S&P 500 tracker) and it goes bust, nuclear war would probably have happened. The only currency worth having in that scenario is tins of beans, with guns to protect those tins of beans.

== Doublepost prevention - post automatically merged: ==

It's already an issue for me - my pensions are down around 13% so far this year (and that's just valuation, not taking inflation into account).
You have to expect massive crashes every so often during an investment lifetime, like ones in 2000 and 2008. The good news, if you are still working, is that you are now buying cheap units.
 
Last edited:

Wynd

Member
Joined
20 Oct 2020
Messages
741
Location
Aberdeenshire
Why are you so concerned about the £85K guarantee? It is meaningless in the context of investing. If you have the most vanilla investment in the world (a S&P 500 tracker) and it goes bust, nuclear war would probably have happened. The only currency worth having in that scenario is tins of beans, with guns to protect those tins of beans.

== Doublepost prevention - post automatically merged: ==


You have to expect massive crashes every so often during an investment lifetime, like ones in 2000 and 2008. The good news, if you are still working, is that you are now buying cheap units.

The madness of complaining about poor bank deposits when you could hold S&P 500 trackers, which are liquid and easily translated in to currency, is one iv been really struggling to get my head around. Then there are Sterling Funds, which are as good as cash, as safe as Gilts, yet, no one really uses them. I don't get it. I just hear family members moaning about how 0.15% isn't enough to retire on, but being simultaneously belligerent to advice about how it could be better invested for a return. "Oh no, that's too risky." Yeah, so is being broke, but I guess we discount that risk, huh?!

The cheap units argument is fine if your earnings and the pricing of the units are the same currency.

For those investing their pensions contributions in S&P or other North American funds, a 20% depreciation in Sterling is not helpful, as the contributions are buying fewer units.
 

DelayRepay

Established Member
Joined
21 May 2011
Messages
2,929
The cheap units argument is fine if your earnings and the pricing of the units are the same currency.

For those investing their pensions contributions in S&P or other North American funds, a 20% depreciation in Sterling is not helpful, as the contributions are buying fewer units.
If you're an active investor, then you can try to mitigate the impact of Sterling depreciation by switching your future investments to GBP. Exchange rate risk is just another risk that needs to be managed when investing.

I appreciate that most people won't be as active in managing their pensions though. And probably don't need to be; whilst I manage my SIPP closely, my returns are only slightly better (or less worse at the moment!) than the returns on my workplace defined contribution pension, which is invested in the pension company's 'default' fund.
 

johncrossley

Established Member
Joined
30 Mar 2021
Messages
4,404
Location
London
Even if you are invested in a GBP denominated fund, the companies in it will be earning money in a variety of currencies, so you will still be affected by currency movements. I don't worry about it.
 

DelayRepay

Established Member
Joined
21 May 2011
Messages
2,929
Even if you are invested in a GBP denominated fund, the companies in it will be earning money in a variety of currencies, so you will still be affected by currency movements. I don't worry about it.

It depends on the fund and which companies it is invested in.

In reality I expect your 'don't worry about it' strategy will produce the same results in the long term!
 

plugwash

Established Member
Joined
29 May 2015
Messages
1,993
For sure, it's all about avoiding inertia and changing plans to suit changing circumstances, isn't it? So much business relies on people not doing this. I know that my "best in the market" instant access savings account no longer is, so I'm going to have to change it .... when I can be bothered!
ISAs have a contribution limit, so depending on how rich you are it may be possible to move all your money into an ISA immediately or it may take decades.
 

Wynd

Member
Joined
20 Oct 2020
Messages
741
Location
Aberdeenshire
It depends on the fund and which companies it is invested in.

In reality I expect your 'don't worry about it' strategy will produce the same results in the long term!

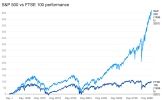
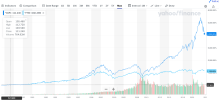
Respectfully, I disagree. The FTSE100, and S&P500 decoupled in 08. You'd be roughly 4x weather in S&P500 now than FTSE100 since 08.

This is just another headwind for the BOE/UK Gov going forwards.

I did not expect such a serious divergence, this was fairly shocking.
 

Attachments

  • Screenshot 2022-09-27 at 10.55.22.png
    Screenshot 2022-09-27 at 10.55.22.png
    207.7 KB · Views: 8
  • Screenshot 2022-09-27 at 10.59.15.png
    Screenshot 2022-09-27 at 10.59.15.png
    344.1 KB · Views: 8

DelayRepay

Established Member
Joined
21 May 2011
Messages
2,929
Respectfully, I disagree. The FTSE100, and S&P500 decoupled in 08. You'd be roughly 4x weather in S&P500 now than FTSE100 since 08.

This is just another headwind for the BOE/UK Gov going forwards.

I did not expect such a serious divergence, this was fairly shocking.
You are entitled to disagree - but I was talking about switching future contributions in the short term to avoid converting GBP to USD at the current exchange rate. How long this approach makes sense for (to me) depends on what happens next.
 

E27007

Member
Joined
25 May 2018
Messages
1,039
The step in the direction of raising of interest rates is a long-overdue correction, a correction to the policy of Quantitative Easing . Quantitative Easing being equivalent to a fresh coat of paint applied to rotten wood
 
Last edited:

DelayRepay

Established Member
Joined
21 May 2011
Messages
2,929
The step in the direction of raising of interest rates is a long-overdue correction, a correction to the policy of Quantitave Easing . Quantitive Easiong being equivalent to a fresh coat of paint applied to rotten wood
It is, however the speed at which it's happening is going to cause rate shock to mortgage holders, especially those coming off low fixed rate deals. In normal times this may be ok, but coupled with the high inflation and pressure on wages it's going to cause real hardship for some families in the short term. We've just seen the Government having to spend billions to intervene in the energy market (and all the parties support intervention - the debate is about the mechanics and how it's funded). Will we, at some point, see the government having to intervene to support mortgage holders?

And yes, I know people could rent instead, but if you rent from a BTL landlord you're going to see their mortgage increases passed on through higher rent, so that's not a solution.

I do agree rates have been too low for too long, but a rapid increase is not good at all. A gradual increase would have been preferable and that's what may well have happened without the B word and the C word!
 

E27007

Member
Joined
25 May 2018
Messages
1,039
It is, however the speed at which it's happening is going to cause rate shock to mortgage holders, especially those coming off low fixed rate deals. In normal times this may be ok, but coupled with the high inflation and pressure on wages it's going to cause real hardship for some families in the short term. We've just seen the Government having to spend billions to intervene in the energy market (and all the parties support intervention - the debate is about the mechanics and how it's funded). Will we, at some point, see the government having to intervene to support mortgage holders?
The Government addiction to the policy of QE, and those low interest rate mortgages fueled and accelerated the escalation of House prices, those coming off fixed-rate deals are facing multiple issues, 1) they have borrowed to purchase a house at a peak or near-peak price, 2) big increases in mortgage payments, 3) long-term negative equity in their purchase.
 

Yew

Established Member
Joined
12 Mar 2011
Messages
7,230
Location
UK
The Government addiction to the policy of QE, and those low interest rate mortgages fueled and accelerated the escalation of House prices, those coming off fixed-rate deals are facing multiple issues,
And most importantly, the drop in housing production, as it turns out that the Private sector didn't pick up the slack when council house production was rolled back in the 80's
 

Bletchleyite

Veteran Member
Joined
20 Oct 2014
Messages
113,234
Location
"Marston Vale mafia"
And most importantly, the drop in housing production, as it turns out that the Private sector didn't pick up the slack when council house production was rolled back in the 80's

Yes, this. Fundamentally if you flooded the market with genuinely affordable homes, prices would reduce. They're high because demand outstrips supply.
 

brad465

Veteran Member
Joined
11 Aug 2010
Messages
11,458
Location
Taunton or Kent
The Government addiction to the policy of QE, and those low interest rate mortgages fueled and accelerated the escalation of House prices, those coming off fixed-rate deals are facing multiple issues, 1) they have borrowed to purchase a house at a peak or near-peak price, 2) big increases in mortgage payments, 3) long-term negative equity in their purchase.
On top of this wages have not kept up with house price increases, so mortgages have been taken out on lower deposit proportions and mortgage values have been higher, while no leeway has existed for allowing mortgage payers to cope with normalising interest rates. To those who say "mortgage rates were much higher in the 90s (or earlier) and we coped them", or similar, don't immediately realise that overall mortgage values were lower and wages were high enough relatively speaking to manage them.
 

Bletchleyite

Veteran Member
Joined
20 Oct 2014
Messages
113,234
Location
"Marston Vale mafia"
On top of this wages have not kept up with house price increases, so mortgages have been taken out on lower deposit proportions and mortgage values have been higher, while no leeway has existed for allowing mortgage payers to cope with normalising interest rates. To those who say "mortgage rates were much higher in the 90s (or earlier) and we coped them", or similar, don't immediately realise that overall mortgage values were lower and wages were high enough relatively speaking to manage them.

You don't have to buy a house, you can rent. If you bought knowing you couldn't afford a return to long term normal interest rates (4-6%) even by stripping pretty much all the luxuries out of your life (my backup for instance is that I could sell the car and pay the loan off, reducing my outgoings by about £250 a month), then you made a very, very stupid decision (or willingly took a risk).

12% would cause a major economic collapse like it did in the 80s, but I'm confident 12% won't happen, unlike a certain two people in the Tory Party the BoE are not stupid.
 

plugwash

Established Member
Joined
29 May 2015
Messages
1,993
If you buy and interest rates go through the roof you are screwed

If you buy and rents go through the roof you are screwed

Pick your poison.
 

Bletchleyite

Veteran Member
Joined
20 Oct 2014
Messages
113,234
Location
"Marston Vale mafia"
If you buy and interest rates go through the roof you are screwed

If you buy and rents go through the roof you are screwed

Pick your poison.

It is easier to move to a smaller place or one in a worse area to save money if you are renting.

Not great, but if you lose an owned home early on you lose everything including the deposit you put in.
 
Last edited:

Islineclear3_1

Established Member
Joined
24 Apr 2014
Messages
6,589
Location
PTSO or platform depending on the weather
If you buy and interest rates go through the roof you are screwed

If you buy and rents go through the roof you are more screwed

Pick your poison.
Because your BTL landlord will pass on the interest rate hike (and more) to you, the poor renter

And those on the shared ownership system will also be screwed as both the rental portion and service charge will go up
 

Yew

Established Member
Joined
12 Mar 2011
Messages
7,230
Location
UK
So, how exactly will changing domestic interest rates fi the actual causes of inflation, Chinese Lockdowns, Ukrainian grain shipments, and Russian oil exports?

I understand that in theory, it it reduces the marginal propensity to consume, by increasing the return on savings; but that seems to vastly misunderstand the financial situation that many people find themselves in after the last decade of wage stagnation and house price increases.
 
Status
Not open for further replies.

Top